

fomo
4.8

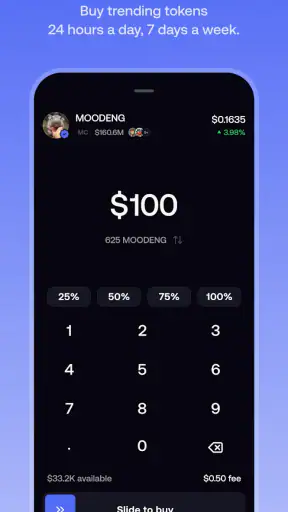
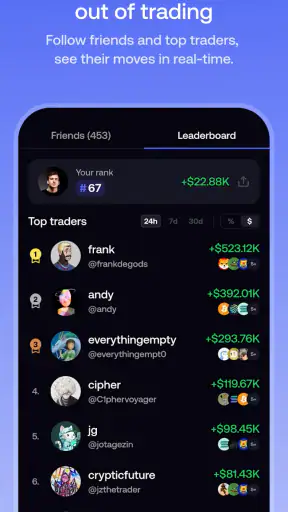
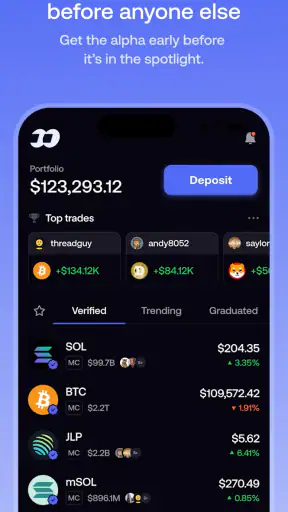
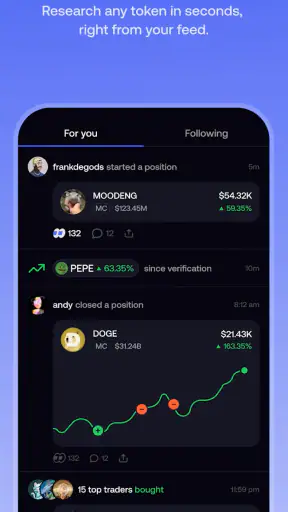
I spent time with fomo as a finance app, paying particular attention to how comfortably it works in different everyday situations rather than judging it only by its social-trading idea. The central appeal is easy to understand: you can keep an eye on what friends are following and notice broader market interest before deciding whether something deserves your attention. That makes it feel more conversational than a traditional portfolio tracker, but it also means the app asks you to separate useful signals from emotional pressure.
Developed by fomo Labs Inc., the app is free and available to Everyone. It has reached over 500 thousand installs and holds a 4.8 average from around 2.8 thousand ratings, which suggests that its basic concept is landing well with a sizeable audience. I tested it with a practical question in mind: can someone use a socially driven finance tool without feeling lost, rushed, or excluded by the way information is presented?
How fomo feels to read and navigate
A social starting point instead of a spreadsheet
The first important distinction is that fomo is not trying to be a conventional banking dashboard. Its identity is built around discovery, people, and trends. Instead of opening to a dense wall of balances and technical charts, I found myself thinking about who was paying attention to what and why that might be worth investigating. For a newcomer, this can be less intimidating than a professional trading terminal, because the social context gives each item a starting point.
That approach is also a readability choice. Financial apps often assume that users already understand tickers, order types, price movement, and portfolio language. A social feed can make the first step feel more familiar, particularly for someone who learns by watching other people. The trade-off is that a feed is not automatically a clear explanation. Seeing a trend or a friend’s interest can tell me where to look, but it does not by itself tell me whether an investment fits my goals.
I recommend treating the main stream as a discovery layer, not as a personal financial plan. When I see something attracting attention, the useful workflow is to pause, open the relevant details, and ask what information is still missing. That habit matters more here than it would in a simple expense tracker, because the social presentation can make a decision feel more urgent than it really is.
Good for scanning, less ideal for deep comparison
On a phone, short pieces of information are naturally easier to scan than long research reports. That benefits users who prefer to check an app briefly during a commute, between tasks, or while waiting in a queue. The concept is also approachable for people who dislike conventional finance interfaces filled with tiny figures and competing panels.
However, social discovery and serious comparison are different jobs. If I want to compare several assets across a long period, build a detailed budget, or study a company before making a carefully documented decision, I would still want a more specialized finance service alongside fomo. Its strength is helping me notice and discuss possibilities; it is not the only tool I would trust for every stage of research.
A useful personal rule is to keep the app in a deliberate “look first, decide later” routine. I might browse it during a short break, save a question mentally, and do the actual evaluation at a calmer time. This prevents the interface from turning an interesting trend into an impulsive action.
What the current release means for day-to-day use
The current version is 1.87.1, and the app was released on July 21, 2025. Those details matter mainly because users should check that their device meets the minimum operating-system requirement of Android or iOS version 9 before planning to use it. People with older phones should pay attention to compatibility, especially if their device is kept for accessibility reasons or cannot be updated easily.
I also appreciate that the app’s free entry point lowers the barrier to trying the social format. A person can explore whether this style of finance information suits them without first committing to a subscription. Still, “free” should not be confused with risk-free. The financial decisions made after using a discovery tool can have real consequences, so I would never let the absence of an upfront app price determine how quickly I act.
Readability for different attention patterns
Users with attention difficulties may find the social structure engaging because it provides a clear reason to open the app: see what is being discussed and decide what deserves further thought. At the same time, a stream of popular ideas can encourage rapid switching from one topic to another. I found it more manageable when I gave myself one narrow purpose per visit, such as checking a familiar contact’s activity or reviewing a single trend.
For users who process information slowly, the most inclusive habit is to avoid making decisions directly from the first screen. Read the item, step away, and return with a written question. This is not a missing feature; it is a way of using a socially stimulating finance app without allowing its pace to dictate yours.
Motor and sensory considerations
Because fomo is designed for mobile use, it can be convenient for people who prefer short touch interactions over a desktop finance platform. That is helpful when I am using one hand, moving between rooms, or checking a small update without opening a laptop. The same mobile format can be demanding for anyone who has difficulty with precise taps, accidental scrolling, or sustained hand movement.
I would use the phone’s own accessibility settings to enlarge text, increase contrast where available, and adjust touch or display behavior to suit personal needs. Those system-level changes can improve comfort, but they may also make a crowded feed require more scrolling. A larger interface is not automatically a better interface if important context becomes separated across several screens.
For people with low vision, the key question is not simply whether text can be enlarged. It is whether the relationship between a person, a trend, and the surrounding financial context remains understandable when less information fits on screen. I would test the app with the device’s preferred text and display settings before relying on it for regular decisions. If labels become clipped or the reading order feels confusing, a larger-screen alternative may be more comfortable.
Users who are sensitive to motion, rapid visual changes, or busy social feeds may prefer brief sessions with notifications and interruptions minimized through the phone’s settings. I would not treat a constantly available feed as something that needs continuous monitoring. In fact, scheduled check-ins are healthier for most people because they reduce the feeling that every new movement deserves an immediate response.
For users with hearing loss, visual information is especially important. A finance app should not be part of a workflow that depends on hearing an alert or understanding spoken commentary. I would rely on visible in-app information and the phone’s visual notification options rather than assuming an audio cue will be enough. Conversely, people who prefer listening because reading is tiring should remember that social finance context can be difficult to interpret without seeing the surrounding details.
Situational access in real life
The strongest everyday scenario for me is a short evening check-in. I can open fomo after work, see which topics have caught my circle’s attention, and make a note of anything I want to research later. The app fits this moment because it turns a vague “what is everyone watching?” question into a focused starting point. I do not need to be at a desk to discover an idea.
A different situation shows its limits. Imagine someone checking the app while boarding public transport, carrying a bag, and dealing with a weak connection or frequent interruptions. Even if the screen itself is readable, the context is poor for financial judgement. A trend that looks compelling in a rushed glance deserves no immediate action. For this reason, I see fomo as suitable for noticing and discussing, but not as a reason to trade while distracted.
It can also help friends with different levels of financial knowledge talk about the same subjects. One person may already follow markets closely, while another is only beginning to recognize names and themes. The social layer gives them a shared starting point. The more experienced user should still avoid presenting personal interest as universal advice, and the beginner should feel comfortable asking what a trend actually means before following it.
For people who travel frequently or switch between home, work, and public spaces, a mobile finance app can be more practical than a desktop-only research routine. Yet situational access includes privacy as well as convenience. I would avoid browsing sensitive financial activity where someone nearby can read the screen, and I would not make account decisions while using an unfamiliar public device. The app’s social nature makes awareness of surroundings particularly important.
Where the social model helps—and where it gets in the way
Compared with a traditional brokerage app, fomo feels more like a discovery and conversation tool than an execution-first workspace. That is an advantage for users who want to understand what people around them are noticing before opening a separate research service. Compared with a news app, it offers a more personal angle: the signal comes from social interest rather than only from headlines. Compared with a portfolio tracker, it is better suited to finding topics than to making a complete record of financial progress.
Those comparisons reveal the main trade-off. Traditional tools tend to be slower and more formal, but they usually encourage a clearer separation between information and action. A social feed can be welcoming and motivating, yet it may also amplify popularity. If I already know that I tend to follow crowds, I would use fomo alongside a neutral source and a personal checklist. If I want detailed budgeting, tax organization, or a complete long-term performance view, I would choose a dedicated finance app instead.
One non-obvious benefit is that the social format can expose me to questions I would not have thought to search for on my own. A friend’s interest may prompt research into an industry or theme outside my normal routine. The corresponding risk is that novelty can look like quality. I would judge the app by the questions it helps me ask, not by how many trends it places in front of me.
Remaining barriers for inclusive use
The biggest barrier is cognitive rather than physical: social proof can feel like reassurance even when it is only evidence of attention. Users who are anxious about missing out may find the name and concept especially persuasive, but that is exactly why they need boundaries. I would turn each discovery into a research task instead of an automatic purchase decision, and I would set a time limit for browsing so the feed does not become a source of constant pressure.
Another barrier is financial confidence. A beginner may understand how to follow a person or topic without understanding volatility, diversification, or the difference between popularity and suitability. The app can make discovery approachable, but it cannot replace foundational learning. Someone who wants step-by-step financial education may be better served by an educational resource first, then use fomo as a way to observe conversations.
There is also a privacy and social-comfort consideration. Not everyone wants their interests to become part of a visible network, and some users prefer finance tools that feel entirely private and administrative. If the social dimension makes you uncomfortable, a conventional tracker or brokerage interface may be a better match. The app’s defining idea is also the reason it will not suit every personality.
People with motor limitations should test whether the pace of scrolling and the precision required for navigation feel manageable before making it part of a daily routine. Those with visual or sensory needs should try their preferred device settings in real conditions, including low light and larger text. I would also recommend using a stable surface or a larger screen when reviewing anything important, rather than attempting to make a careful decision one-handed.
For users who rely on assistive technologies, the practical experience may depend on the phone, operating system, and chosen settings. I would approach the app with a short trial: open the main areas, move through the most important information, and confirm that the reading order and controls make sense. If that basic path is tiring or unclear, no amount of social discovery is worth forcing the workflow.
Who should try it, and who should skip it
I think fomo is a good fit for curious users who want a social way to discover financial topics, especially people who find conventional market dashboards cold or overwhelming. It can also suit friends who enjoy comparing what they are watching, provided everyone treats the conversation as a source of ideas rather than a substitute for personal judgement.
I would be more cautious recommending it to someone who is highly reactive to popularity, is looking for a complete budgeting system, or expects a single app to provide deep research and careful portfolio management. It is also not my first choice for a person who needs a quiet, private, low-stimulation finance experience. In those cases, a traditional tracker, educational service, or research-focused platform may offer better control.
The free price makes experimentation straightforward, and the Everyone age rating makes the app broadly approachable. Still, broad availability does not mean every user will find the same level of comfort. The right test is whether you can browse without feeling pushed, read the information in your preferred format, and leave the app with better questions rather than stronger impulses.
My inclusive verdict
After using it, I see fomo as a friendly front door to financial discovery, with accessibility shaped mainly by how deliberately it is used. Its social design can reduce the intimidation of starting from a blank screen, and its mobile format works well for quick, informal check-ins. The app is especially useful when I want to notice what people are discussing and then take that idea elsewhere for proper evaluation.
Its limitations are equally important. A trend is not a recommendation, social attention is not proof of suitability, and a compact mobile feed cannot serve every research or accessibility need. Users who need detailed controls, a calmer interface, or a full financial record may be happier with a more specialized alternative. I would also avoid using it during rushed or distracting moments, regardless of how easy the first screen feels.
My bottom line is simple: use fomo to widen your awareness, not to outsource your judgement. With scheduled browsing, personal research notes, and device settings adjusted to your needs, it can be an approachable addition to a finance routine. Without those boundaries, the same social energy that makes it interesting can make it harder for some people to slow down and decide clearly. For me, that balance defines the app: worthwhile for discovery, useful for conversation, and best when paired with a calmer tool for serious financial decisions.
4.8
123.00 Reviews
Pros
- Helps users discover trending events and activities nearby.
- Useful for finding last-minute plans with friends.
- Simple interface makes browsing opportunities quick and easy.
- Can encourage users to try experiences outside their usual routine.
- Helpful for staying aware of popular local happenings.
Cons
- Some listings may be unavailable or outdated by the time you check.
- Popular events can create pressure to join unnecessarily.
- Availability and features may vary depending on your location.
- Notifications could become distracting if too frequent.
- Some experiences may require extra purchases or reservations.


